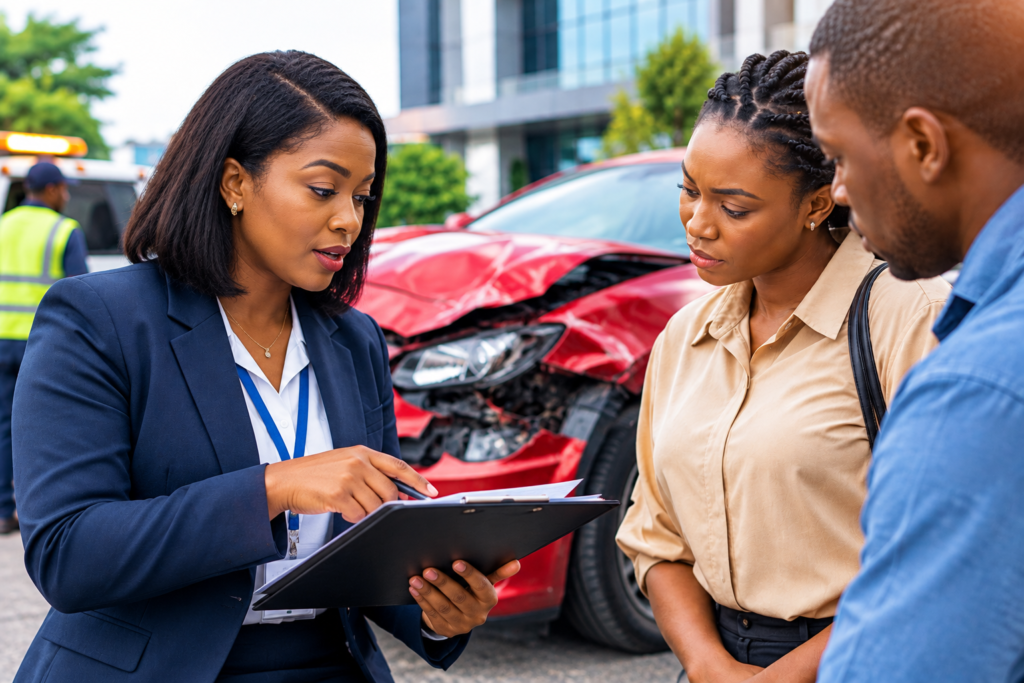
When an unexpected loss occurs—whether it is a fire, accident, theft, damaged goods, or a claim against your business—it is natural to wonder what to do first.
Having insurance is important, but understanding how to use your policy when you need it matters just as much. The claims process does not have to be overwhelming. These steps can help you get started:
1. Notify your insurer or broker promptly.
Report the incident to your insurance company or broker as soon as reasonably possible. Share the basic facts and ask what to do next.
For example:
“There was a fire at our warehouse yesterday evening, and some stock and equipment were damaged.”
Check your policy for any notification deadlines, as delays can sometimes complicate a claim.
2. Prevent further damage
Take reasonable steps to protect the property and prevent the situation from getting worse. This might mean shutting off a water supply, securing premises after a break-in, moving a damaged vehicle to a safe location where appropriate, or separating damaged goods from unaffected stock.
However, avoid throwing away or repairing damaged items until your insurer or broker advises you to do so. The property may need to be inspected or assessed.
3. Document what happened.
Take clear photographs and videos of the damage, and keep all relevant records. Depending on the circumstances, these may include:
•Police or fire service reports
•Medical reports, where applicable
•Invoices and receipts
•Stock and asset records
•Repair estimates
•Delivery and shipping documents
•Your policy documents
For a business claim, photographs may not be enough to establish the value of the loss. Stock records, invoices, and other supporting documents can make a significant difference.
4. Complete the claim form accurately.
Your insurer may ask you to complete a claim notification or formal claim form. Provide information honestly and avoid guessing or overstating the value of the loss.
If you are unsure about any part of the form, ask your broker or insurer for clarification before submitting it.
5. Provide the requested documents.
The documents required will depend on the type of claim and the terms of your policy. For example:
•Motor claims: police report where applicable, driver’s license, vehicle documents, repair estimate, and photographs
•Fire claims: fire service report, police report where applicable, stock and asset records, invoices, and photographs or videos
•Marine cargo claims: invoice, bill of lading, packing list, delivery documents, survey report, and other relevant shipping records
Your insurer may request additional information based on the circumstances.
6. Cooperate with the assessment
For some claims, the insurer may appoint a loss adjuster or another professional to assess what happened and the extent of the loss. Cooperating with this process and providing reasonable access to relevant information or property can help the claim move forward.
An assessment does not automatically mean your claim will be rejected. It is usually part of determining what happened, whether the loss is covered, and the amount payable under the policy.
7. Keep records and follow up.
Keep your claim reference, documents, correspondence, and dates of communication organized. If you have not received an update, it is reasonable to ask about the current status of your claim.
A good insurance broker can also help explain the process, communicate with the insurer, and assist when questions arise.
Five things to avoid after an insurance loss
•Do not hide or leave out important information.
•Do not exaggerate the value of your loss.
•Do not dispose of damaged property without advice.
•Do not unnecessarily delay reporting the incident.
•Do not assume that every loss is covered simply because you have an insurance policy.
The terms, conditions, exclusions, limits, and requirements of your policy all matter. If you are unsure about your cover, review the policy and speak with your insurer or broker before a loss occurs.
Insurance is not only about buying a policy. It is also about understanding what the policy covers and knowing what to do when you need to rely on it.
Have you ever made an insurance claim in Nigeria? What was the most difficult part—the paperwork, understanding the cover, or following up on the claim? Share your experience; it may help another business owner.
The Role of an Insurance Broker During a Claim
This is where having the right insurance broker can make a significant difference.
A broker doesn’t simply help you arrange insurance. A good broker can also help you understand your policy, guide you through the claims process, and advocate for your interests when dealing with the insurer.
At Liberty & Trust Insurance Brokers, our goal is to help clients understand their insurance protection before a loss happens and provide professional support when they need to make a claim.
Insurance is not just about buying a policy.
It is about having the right protection, understanding that protection, and knowing how to activate it when you need it most.